Age Verification at Online Casinos: How It Typically Works
Online casinos perform identity verification to comply with gaming law. The process combines document checks, database matches, and third-party verification services. Understanding how it works reveals how and why it sometimes fails.
Jump to a section
Richard Thaler has written extensively about how people make decisions when stakes are high and information is uncertain. Age verification at online casinos is a perfect example of this asymmetry. The operator knows they face regulatory fines if they accept underage players. The player knows they face account closure if they lie. Yet the system itself operates on assumptions about human honesty that behavioral economics tells us are fragile.
Most online casinos in regulated markets use a three-stage verification process: initial self-declaration, document verification, and database cross-check. Let me walk through what happens at each stage and why each stage has weaknesses that behavioral factors exploit.
Stage One: Self-Declaration and Initial Screening
When you register at an online casino, you provide your date of birth. The system flags you as either underage or age-eligible. This is instant and automated. No verification has occurred; you have simply claimed an age. From a behavioral perspective, this stage is trivial. Most honest players report accurately. But the existence of this gate creates a first test: if you pass it, later stages assume your initial claim was true.
This is loss aversion at work (Kahneman and Tversky, 1979). An underage player who sees the age gate has to weigh the loss of access against the effort of lying. For a minor with no gambling history, the loss is abstract. The effort to proceed (a false birthdate, a parent's credentials) is concrete. Loss aversion tilts the decision toward providing false information.
Stage Two: Document Verification
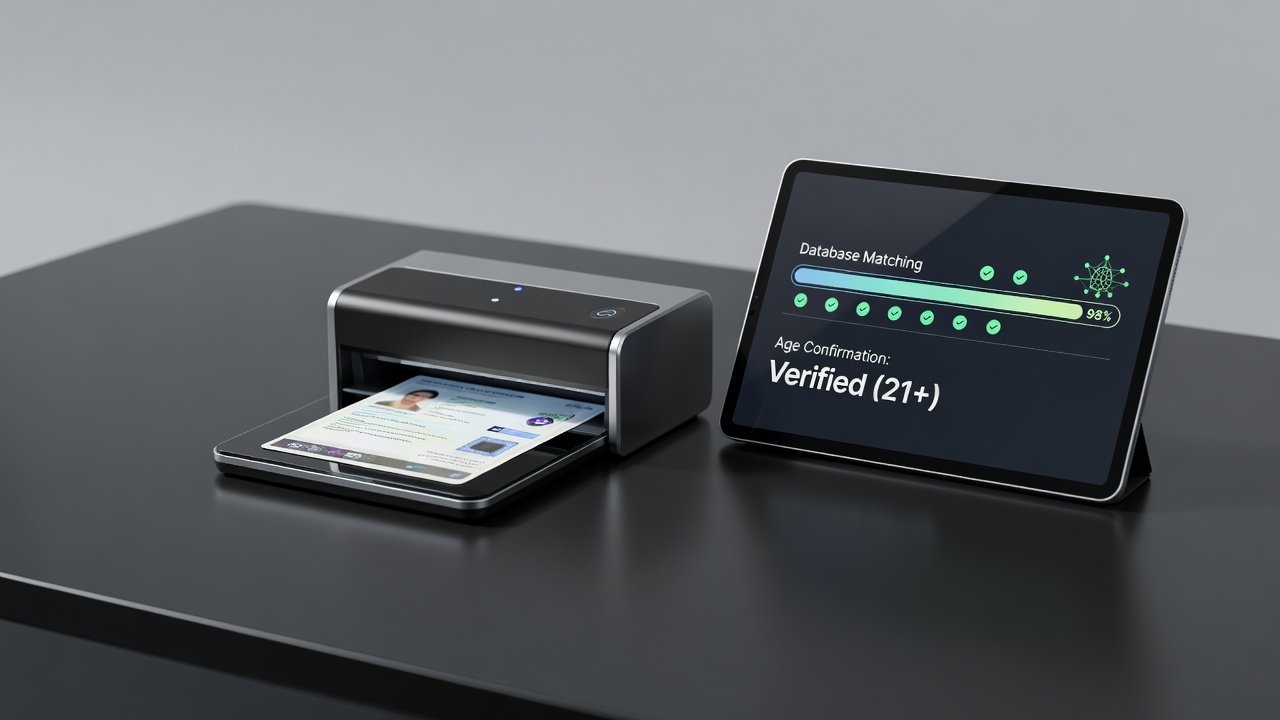
Once the account is created, you deposit money or attempt a withdrawal. At that point, regulated operators request identity documents: a government-issued ID, passport, or driver's license. The casino (or a third-party service contracted by the casino, such as Socure or Onfido) performs optical character recognition (OCR) on the document.
The OCR process extracts your date of birth, name, and ID number. A human reviewer cross-checks the document against the self-reported information. Any significant mismatch triggers a manual review or account freeze.
Behaviorally, this stage works better than self-declaration alone. The document creates accountability. But the system assumes the document is genuine. Behavioral economics suggests that when stakes rise, people innovate. Underage players may:
- Use a sibling's ID (mental accounting: "I'm borrowing, not stealing").
- Use forged documents (behavioral finding: younger people underestimate detection risk; see Ariely and others on dishonesty escalation).
- Use a parent's ID with permission (boundary-crossing: once one rule is broken, others seem smaller).
Despite these gaps, document verification catches the majority of non-compliant players. The operator now has your legal name and birthdate embedded in their KYC file.
Stage Three: Database Cross-Check and Third-Party Verification
Major operators (DraftKings, BetMGM, FanDuel) use third-party verification services that cross-check your identity against public records databases and credit bureaus. Services like Socure, Thomson Reuters Kyros, or Experian perform real-time verification using Social Security number (in the US), credit history, and public records.
This stage is expensive (5-15 dollars per verification for the operator) but highly effective. If you claimed you were born January 1, 1990, and Social Security records show you were born January 1, 2005, the mismatch is flagged. Account restrictions are imposed until resolution.
The behavioral insight here is threshold effects. An operator that invests in third-party verification creates a sharp boundary between compliant and non-compliant behavior. Underage players face a choice: abandon the attempt or use genuine credentials, which immediately triggers age-gate rejection.
Regulated markets in the UK, Malta, and Curaçao require this third-party verification for deposits over a threshold amount (typically 2,000 GBP or equivalent). Unregulated operators skip this stage entirely, which is where enforcement gaps emerge.
Why Age Verification Sometimes Fails
The system holds well against casual falsehood but remains vulnerable to determined deception. An underage player with access to a parent's genuine identity documents and willingness to impersonate can pass all three stages. The mental accounting allowing this ("It's technically legal if I use my parent's name") is a known behavioral pattern: people rationalize boundary violations when the barrier feels arbitrary.
Furthermore, the system assumes documents are not stolen. A minor using a classmate's genuine ID will pass document and database verification. Behavioral detection of this scenario requires tracking unusual patterns: a single ID used to create multiple accounts, or rapid account cycling (opening, depositing, withdrawing, closing).
Major UK operators have invested in behavioral monitoring systems that flag these patterns. The UKGC now requires operators to detect and report suspicious account creation patterns. This moves verification from static (Is this document real?) to dynamic (Does this account behave like a real person?).
The honest summary: age verification at online casinos works well for honest players and casual deception, moderately well for determined underage access attempts, and poorly for stolen identity scenarios. The regulatory framework assumes bad faith is manageable through documentation and cross-checks. Behavioral economics suggests that assumption holds for most people most of the time, but it holds differently across age groups and regulatory jurisdictions.
Subjects in this guide
Pass it on
Choosing where to play? The casino ratings score each site on 6 checks, in half stars.
See the ratings